Between January and September, our teams completed 148 deals across 13 countries, worth €8.3bn combined and up 12% on last year.
We raised €1.6bn of debt for clients and worked with more than 45 different private equity houses, both to give our clients access to investment and to help funds realise the value of businesses they have backed.
LSEG’s Q3 2026 league tables place Clearwater tenth in Europe by deal volume¹, making our teams one of the most active advisers in Europe.
“Industrials are in demand”
Industrials & chemicals was our fastest-growing sector, with 39 deals against 29 in the same period last year. Much of that came from larger industrial groups buying specialist businesses to add a capability, often across borders. What they’re usually paying for is know-how that would take years to build in-house.
“Steady, but selective”
Across Europe, the number of deals has held roughly steady. Deal numbers across LSEG’s European ranking fell 1.4% on last year¹, and Mergermarket² reports mid-sized deal activity across EMEA level with 2025.
So, what does that mean for a mid-market business? The market hasn’t boomed, and it hasn’t stalled. Good businesses are still selling and still raising money, but buyers are choosy. Private equity investment in Europe rose 18% by value in the first nine months². US investors were involved in a record 45.7% of European private equity deal value in Q3³, so international capital is still coming into Europe.
What the market is saying
“Private equity is still investing, and our relationships open the door”
Private equity was involved in two-thirds of our deals, across more than 45 different houses. What’s changed is which side of the table they’re on. Many funds have held businesses for longer than they planned, and their own investors want to realise that value, so more of them are selling. The headlines state that European private equity exits rose 30% by value this year². We’ve seen that first-hand, selling De Wave Group for Platinum Equity and Global Vehicle Group for H2 Equity Partners and fellow shareholders. Private equity is still buying too. For owners, that means capital is there, but there are also more businesses competing for the same buyers’ attention.
“The best buyer isn’t always next door”
Close to four in ten of our deals were cross-border. KE Fibertec in Denmark was bought by US-based Rite-Hite. Airedale Group in the UK went to Germany’s Brenntag. Cedar Automotive in Ireland joined Portugal’s Salvador Caetano Group. The lesson for owners is simple: if you only look for buyers in your own country, you may miss the one who values your business most. That’s why our teams in 13 countries work as one.
“Industrials are in demand”
Industrials & chemicals was our fastest-growing sector, with 39 deals against 29 in the same period last year. Much of that came from larger industrial groups buying specialist businesses to add a capability, often across borders. What they’re usually paying for is know-how that would take years to build in-house.
“Steady, but selective”
Across Europe, the number of deals has held roughly steady. Deal numbers across LSEG’s European ranking fell 1.4% on last year¹, and Mergermarket² reports mid-sized deal activity across EMEA level with 2025.
So, what does that mean for a mid-market business? The market hasn’t boomed, and it hasn’t stalled. Good businesses are still selling and still raising money, but buyers are choosy. Private equity investment in Europe rose 18% by value in the first nine months². US investors were involved in a record 45.7% of European private equity deal value in Q3³, so international capital is still coming into Europe.
Some of the deals behind the numbers
- Sedex: Apax’s acquisition of the business from LDC (UK)
- EX NIHILO: secondary LBO with L Catterton (France)
- Bovemij Group: BOVAG’s sale of the business to a.s.r. (Netherlands)
- De Wave Group: Platinum Equity’s sale of the business to Renaissance Partners (Italy)
- Airedale Group: sale to Brenntag (UK)
- Vervent Audio Holding: Barco’s acquisition of the business from Alpha Private Equity (France)
- Cedar Automotive Group: sale to Salvador Caetano Group (Ireland)
- KE Fibertec: sale to Rite-Hite (Denmark)
- SOAL Marine: partnership with FSN Capital (Sweden)
Top sectors by deal count
Business Services
32
deals completed with €2.1bn in deal value
Industrials & Chemicals
39
deals completed with €2.5bn in deal value
Tech & Tech Services
42
deals completed with €1.5bn in deal value
Bruce Weir, COO, commented on Q3 results:
“Every one of these deals reflects a great team putting in the hours, often on long and complex processes, and supporting each other across offices to get it done. I’m proud of how hard our people have worked this year, and pleased to welcome the colleagues who have joined us along the way.”
Sources
¹ LSEG Deals Intelligence, Q3 2026 European M&A league tables
² Mergermarket, Global M&A momentum slows in 3Q26 after record-chasing first half, 1 October 2026
³ PitchBook, Q3 2026 European PE Breakdown, 5 October 2026
Investing in our people
This year we welcomed Daniel Schreiber as a Partner in Zurich, bringing consumer, food & beverage and tech experience to our DACH team, and two new Directors: Diogo Lemos in Lisbon, with more than 15 years in M&A, and Emiel van der Wekken in Amsterdam, who focuses on industrials, business services and healthcare. In Sweden, Henrik Falkenby, who joined us in 2017, was promoted to Partner and leads our Swedish tech & tech services team.
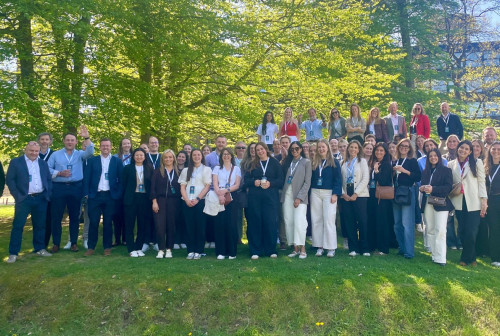
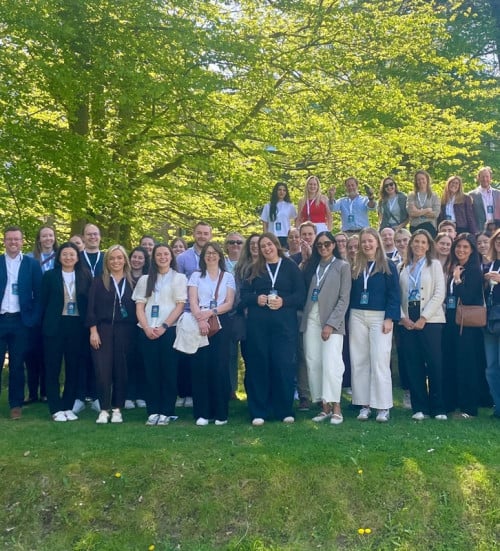
Culture matters as much as hiring. In a business where our people are the product, it shapes how we attract talent, how we work with clients and how motivated our teams are in every office. It is also a real differentiator for our employer brand. At ClearVision 2026, our annual culture and inclusion event, colleagues from across our offices spent two days in Brussels focusing on how we lead, how we perform as one firm across borders, and how we sustain our people to deliver our vision. We started from a strong base: in our 2025 Your Say survey 99% of colleagues said they were proud to work at Clearwater and engagement reached 95%. In an increasingly competitive market, a strong, shared culture and consistent leadership are what set a high-performing M&A adviser apart.
Bruce Weir, COO, commented on Q3 results:
“Every one of these deals reflects a great team putting in the hours, often on long and complex processes, and supporting each other across offices to get it done. I’m proud of how hard our people have worked this year, and pleased to welcome the colleagues who have joined us along the way.”
Sources
¹ LSEG Deals Intelligence, Q3 2026 European M&A league tables
² Mergermarket, Global M&A momentum slows in 3Q26 after record-chasing first half, 1 October 2026
³ PitchBook, Q3 2026 European PE Breakdown, 5 October 2026