About Kaffekapslen
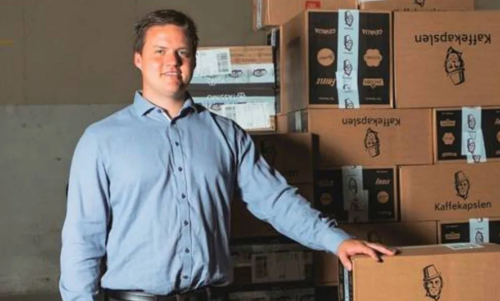
Kaffekapslen is the largest distributor of coffee capsules in Denmark, Sweden and Norway. Founded by the entrepreneur Morten Ravn in 2011, in 2016 Kaffekapslen gained a co-owner in Anders Balmer, who until then had been the company’s auditor.
In 2021, Anders and Morten sold 55 % of Kaffekapslen to the private equity firm Ceder Capital. Morten has since left the management team, but Anders remains in place as CEO.
We already had a clear strategic direction before the equity firm appeared on the scene, but it goes without saying, that it’s given us more peace of mind to think more long-term.
Are the day-to-day operations any different today, than before selling to the private equity firm?
No, actually. However, there are some structural elements that you need to keep on top of when you’re part of a private equity firm, which we hadn’t introduced ourselves, such as appointing a board of directors. After all, it makes good sense to do the things that need to be done.
Has the partnership with a private equity firm led to any changes in your strategy or objectives?
We already had a clear strategic direction before the equity firm appeared on the scene, but it goes without saying, that it’s given us more peace of mind to think more long-term. We’ve invested a lot in the future. For example, employing new staff for the company. We wouldn’t have dared to do that to the same extent before. Having the support to back up our decisions means a lot.
Private equity funds are known to be highly data-driven. Have they had stringent reporting requirements?
We were already very data-driven because we’re a market-dependent company. During the sale process, we also identified a lot of things we wanted to do with our data and opportunities we were keen to exploit, but we got help with other things that we wouldn’t have been able to improve on our own. For example, we want to open a warehouse abroad and this is where the equity firm has the geographical network that we need to achieve this objective.
Why did you opt for the private equity route, rather than selling to a strategic buyer?
We had actually expected to opt for a strategic buyer before we started the process, but we found that with a strategic investor, we would simply end up following their strategy. We already had a strategy that worked, and we were comfortable with, and that’s the strategy the private equity firm bought into. At the same time, we took some risks off the table and brought someone else on board to make us stronger.
Is there a difference between how you viewed private equity firms before the process started, and how you view them now that you are partnered with one?
I thought that a private equity firm would come in and destroy everything before selling up a few years later, rather than helping the business grow and improve, but it’s the complete opposite. They understand our business and appreciate that good things take a long time. I’m actually the one who gets impatient if I think things are going too slowly. It’s really reassuring having their support.
Now that you have been working with a private equity fund for a while, what do you think are the greatest strengths of the private equity fund model?
Without a doubt, the greatest strength is that we recognise each other’s strengths. As I said before, I was concerned that a private equity firm would be made up of people who wanted to interfere and force decisions through, but I’ve certainly been proven wrong.
What is the best advice you would give to someone considering selling a majority stake to a private equity fund?
My best advice is, of course, to make sure you’re in full control of your business. An equity firm can’t help you with that. It’s a bit like giving a bad cyclist EPO; there’s no real benefit. If your strategy is simply to “grow”, this isn’t going to be enough if you don’t know how. So, whatever happens, it’s going to be hard to achieve, and then you need to have confidence in yourself. It’s not compulsory to let others take over. If you’ve reached the point of having had enough and want to get out of the company soon, then the private equity route is not the one for you.
Many e-commerce businesses experienced extraordinary activity during the pandemic. How are things now that the market has normalised?
As the percentage growth of the market has slowed, so has our percentage growth. If we didn’t have the good market insights that we do, we’d probably have panicked. For us, the rising prices of raw materials are more of a concern right now.
The Clearwater difference
1 Maintain local relationships while having a global outlook
2 Be flexible enough to accommodate all stakeholders
3 Recognise the truly differentiating features of a business
4 Engage across all stakeholders to identify areas of opportunity
Clearwater advisers



Success stories