When people talk about data centres, they usually picture vast, windowless buildings packed with servers, humming away on the edge of a city.
What’s less visible is the ecosystem of specialist services that make those buildings possible and keep them operating. As global capacity expands at pace, we’re seeing that much of the real M&A momentum sits not in the assets themselves, but in the design, build and run services that support them.
At Clearwater, we’ve advised across this value chain, working with businesses involved in grid connectivity, power infrastructure, specialist engineering, networking, cooling optimisation, monitoring and long-term operational support. Increasingly, we’re seeing these services businesses attracting intense buyer interest.
The overlooked market: design, build and run
A helpful way to understand the market is through the data centre lifecycle.
Design: laying the foundations
The lifecycle starts when demand for capacity in a geography is established and, crucially, when access to power is secured. In many markets, power availability is the gating factor for development.
From there, the design phase can be lengthy and complex. It includes architectural and engineering services, planning and permitting, compliance, and the technical decisions that determine long-term efficiency and resilience.
Three fundamentals shape this phase:
- Securing sufficient and reliable power
- Ensuring proximity to fibre and network infrastructure
- Selecting locations that balance latency, cost and deliverability
The outputs from design influence operating cost, sustainability performance and future upgrade potential, so getting this right matters.
Much of the real M&A momentum sits not in the assets themselves, but in the design, build and run services that support them.
Build: specialist capability at scale
Build is where complexity increases. Large campuses can take years to complete and involve a wide range of trades and specialist disciplines.
Services consumed during this phase include:
- High-voltage and critical power installation
- Civil and structural works
- Fibre, cabling and network installation
- Fire detection and suppression systems
- Security and access control
- Commissioning and testing
This is a capital-intensive stage where execution risk is high. Delivery timelines are tight and failure has commercial consequences, which is part of why experienced, referenceable specialists are in such strong demand.
Run: long-term operational resilience
Once commissioned, the run phase begins. Data centres consume a wide range of ongoing services throughout their operating lives.
These include facilities management, preventative maintenance, monitoring, energy management, system upgrades and compliance reporting. Availability targets are demanding and service level agreements leave little room for error. As more sites come online, the need for specialist operational support grows in parallel.
Why build-out continues to accelerate
Longer-term drivers such as cloud migration, streaming and real-time analytics have underpinned growth for years. More recently, AI at scale has become the defining catalyst.
Training and running large models requires significantly more compute intensity than traditional enterprise workloads, which translates directly into higher power density and greater cooling demand. Operators are investing heavily in AI-ready capacity and the associated infrastructure.
Most sector commentators expect capacity and power requirements to increase materially over the next five years. For the services market, that means sustained demand across design, build and run.
More recently, AI at scale has become the defining catalyst.
Why M&A is concentrating in the services layer
We’re seeing three consistent themes driving deal activity across the supply chain:
1. Speed to market
Building specialist capability organically takes time. In a market where demand is rising quickly, buyers and investors often prefer to acquire established teams with proven track records.
That allows them to secure scarce engineering talent, gain delivery credibility and access forward pipelines more quickly than building from scratch.
2. Geographic expansion
Data centres are physical assets that require local delivery capability, and because latency and resilience require geographic distribution, operators need capacity in multiple regions.
Services providers therefore need presence where development is happening. Acquiring local specialists becomes an efficient way to enter new territories and support clients’ international build-out plans.
3. Broader service coverage
As projects become larger and more complex, delivery risk increases. Some buyers and investors are expanding their service coverage to reduce handoffs and improve accountability across projects.
In certain cases, acquiring adjacent capabilities supports a more integrated offering and provides greater certainty around execution.
What buyers and investors are prioritising in data centre services assets
Across recent transactions and ongoing discussions, several attributes consistently attract interest.
Clear data centre focus
Businesses that have designed their delivery models around data centre environments tend to stand out. Buyers and investors value providers who can demonstrate repeat experience, strong reference ability and an established go-to-market strategy aligned to operators and developers.
Mission-critical expertise
Critical power, fire and life safety systems, security, controls and monitoring are essential components of any facility. Providers that are recognised as leaders in specific niches within defined geographies often command strong attention.
Customer relationships and pipeline visibility
In such a fast-moving market, relationships matter. Being embedded with major developers and operators provides visibility on future projects and strengthens an investment case.
Systems and optimisation capability
Data centres are highly engineered environments where every watt is scrutinised. Monitoring, control and optimisation systems play a central role in operational performance.
Businesses that can help operators measure, manage and improve efficiency are increasingly attractive to investors.
In a market where demand is rising quickly, buyers and investors often prefer to acquire established teams with proven track records.
Sustainability: scrutiny that becomes a commercial driver
Data centres attract scrutiny around energy consumption and environmental impact, and at the same time, operational efficiency and sustainability are closely aligned.
Reducing energy usage lowers both cost and carbon intensity. Improving cooling performance enhances reliability and environmental performance. Better monitoring supports governance and regulatory compliance.
That alignment is driving investment into:
- Cooling and thermal optimisation
- Energy modelling and reporting
- Power management systems
- Compliance and governance services
As regulatory expectations evolve, specialist consultancies and managed services providers focused on environmental performance are likely to see increasing demand.
The next wave: run-phase services and lifecycle upgrades
Build activity shows no sign of slowing, and as more facilities become operational, demand for run-phase services will increase.
The installed base is expanding, and with that comes a growing requirement for maintenance, upgrades, monitoring and optimisation. Older facilities will also undergo technology refresh cycles to improve efficiency and performance.
Specialists focused on servicing, maintaining and improving operational facilities are therefore well positioned for continued interest.
Why Clearwater
Navigating the data centre services market requires a deep understanding of the lifecycle, the buyer and investor universe with the nuances that drive value.
Our team at Clearwater has advised on transactions across the design, build and run spectrum, supporting businesses with exposure to critical power, connectivity, specialist engineering and operational optimisation. This experience enables us to position assets clearly, engage the right buyers and run competitive processes in a market that is increasingly global and capability-driven.
The data centre boom is visible in skylines and power grids across Europe and beyond. Behind that growth sits a dynamic services ecosystem where M&A momentum remains strong. As capacity continues to scale, we expect demand for specialist capability to remain firmly in focus.
If you’re operating in the data centre services ecosystem and considering your next strategic step, we’d welcome a conversation. Whether you’re planning for growth, exploring investment, or preparing for exit, our team can help you position your business to capture the strongest outcomes in this fast-moving market.
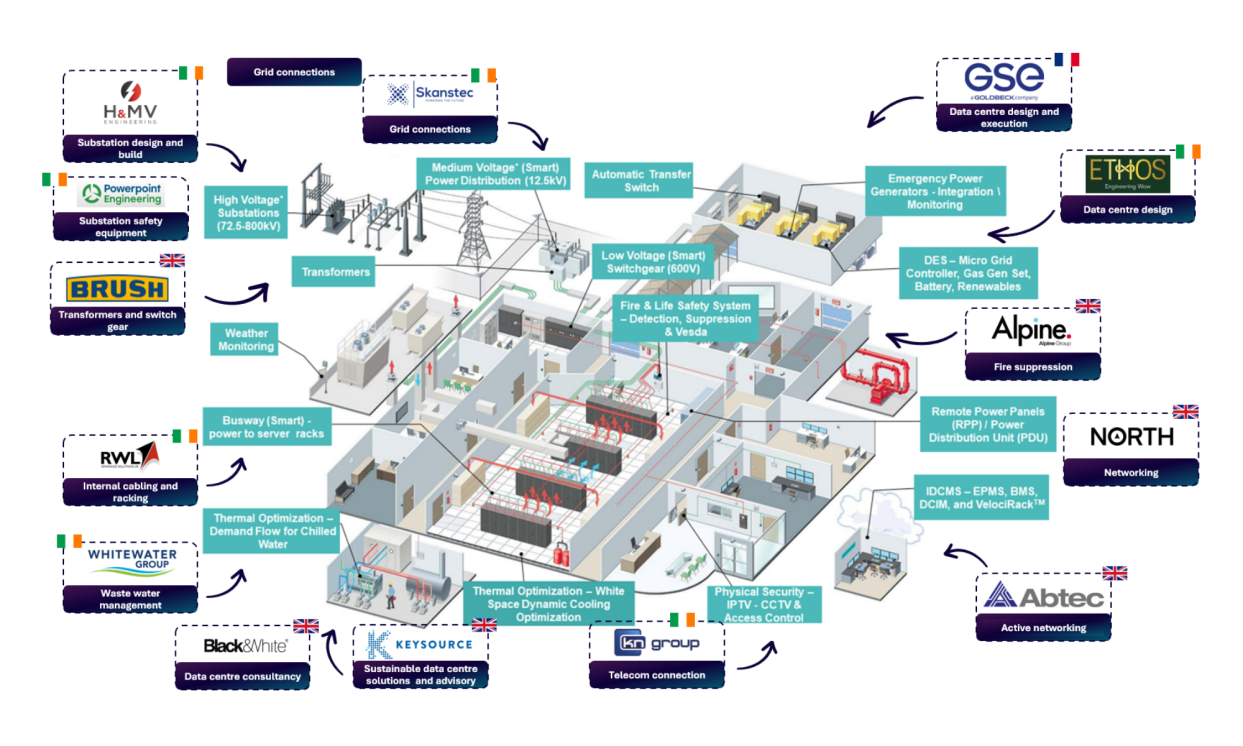
Our data centre value chain transaction expertise

AUTHOR
Robert Umpleby
Director
I began my advisory journey eight years ago. Fuelled by a passion for all things tech, I quickly found my natural home within tech M&A, where I now dedicate the majority of my time. I am fortunate to be part of an established tech team at Clearwater that has an enviable track record of delivering great results for inspiring businesses and allows me to work with passionate and ambitious clients.
Recent data centre transactions

Strategic investment accelerates integrated technology platform in a fast‑paced market
Adviser to Abtec Group on its investment from Cow Corner

Leading UK environmental TICC specialist receives investment to strengthen market-leading position
Adviser to the shareholders of HSL Compliance
Majority sale of Rutland-backed JSM Group to TowerBrook Capital Partners
Adviser to the shareholders of JSM Group on its sale to TowerBrook Capital Partners