Deployment pressure meets a more complex market
Private equity remains one of the most influential forces in the M&A landscape, but the environment it’s operating in has shifted meaningfully. Uncertainty hasn’t eased, but evolved, and funds are learning to operate within it rather than wait for it to pass.
Greater scrutiny, sharper focus
Despite the need to deploy capital, private equity firms are approaching deals with more rigour than ever. Investment committees are asking tougher questions, diligence is deeper, and timelines are often longer.
At the centre of that scrutiny is one dominant theme: resilience.
AI has become a defining consideration in almost every investment decision. Businesses are no longer judged purely on growth or recurring revenue, but on how exposed they are to disruption and how well positioned they are to adapt.
This is particularly evident in software and technology, where the conversation has shifted from growth potential to defensibility. Increasingly, investors are looking for businesses with strong customer “stickiness”, service layers, or hybrid models that combine technology with human expertise.
More broadly, macro factors such as inflation, cost pressures, and geopolitical uncertainty continue to feed into decision-making. Funds aren’t stepping back from deals, but they are taking more time to get comfortable with risk.
This is shaping behaviour across the board. Many funds are still holding larger portfolios than they would like, with extended hold periods stretching beyond historic norms. At the same time, pressure from LPs to return capital ahead of future fundraises is building.
The result is a more complex balancing act. Firms are managing existing investments, looking for exit routes, and trying to create capacity for new opportunities, all at once.
While deal flow is improving and pipelines are stronger than they were this time last year, deployment isn’t uniform. Some funds are under pressure to invest and are prepared to move quickly, while others, particularly those further along in their deployment cycle, are taking a more measured approach.
This is creating a degree of polarisation in the market. In certain situations, funds with strong conviction and deployment pressure are willing to stretch on valuation to secure the right asset. Others remain disciplined, focusing on price and long-term value.
“We’re seeing portfolios that are significantly larger than they should be. That creates a knock-on effect, where teams are stretched and don’t have the time to focus on new opportunities in the same way.”
Marcus Archer, Managing Partner
Greater scrutiny, sharper focus
Despite the need to deploy capital, private equity firms are approaching deals with more rigour than ever. Investment committees are asking tougher questions, diligence is deeper, and timelines are often longer.
At the centre of that scrutiny is one dominant theme: resilience.
AI has become a defining consideration in almost every investment decision. Businesses are no longer judged purely on growth or recurring revenue, but on how exposed they are to disruption and how well positioned they are to adapt.
This is particularly evident in software and technology, where the conversation has shifted from growth potential to defensibility. Increasingly, investors are looking for businesses with strong customer “stickiness”, service layers, or hybrid models that combine technology with human expertise.
More broadly, macro factors such as inflation, cost pressures, and geopolitical uncertainty continue to feed into decision-making. Funds aren’t stepping back from deals, but they are taking more time to get comfortable with risk.
“Everything is being looked at through the lens of AI disruption. It’s not just about growth anymore, it’s about resilience and how defendable the business is.”
Marcus Archer, Managing Partner
Evolving deal structures and capital strategies
While the fundamentals of dealmaking remain intact, there are clear shifts in how transactions are being structured.
One notable development is the increased use of preferred equity structures. These allow private equity firms to offer a higher headline valuation, while making sure their capital ranks ahead of management in the event of an exit.
This approach is serving two purposes. It provides flexibility in valuation discussions, and it reinforces alignment, ensuring management teams are fully committed to delivering the next phase of growth.
At the same time, leverage levels at entry are generally lower than in previous years. In a more uncertain environment, funds are prioritising balance sheet flexibility over maximising returns through debt.
This is also enabling a more proactive approach to growth. With less debt in place, businesses have greater capacity to pursue acquisitions, invest in expansion, and respond to market opportunities as they arise.
Conviction-led investing and earlier engagement
Another clear shift is how private equity firms are identifying and pursuing opportunities.
Rather than casting a wide net, funds are becoming more focused. Most are narrowing in on a small number of sectors where they have strong conviction and a clear value creation strategy.
This is being supported by more proactive, “outside-in” work. Funds are building relationships with target businesses and advisers well before a formal process begins, and in many cases are forming views on assets months or even years in advance.
The impact is significant. By the time a process launches, the most prepared buyers are already well positioned to act decisively.
Buy-and-build: from strategy to necessity
Buy-and-build strategies are becoming even more central to private equity playbooks.
While they’ve long been a feature of the market, they’re now being used more deliberately as a tool for both growth and risk management. In sectors where organic growth is harder to achieve, acquisitions provide a faster route to scale and value creation.
At the same time, diversification through add-ons is helping businesses become more resilient, whether by expanding service lines, entering new geographies, or reducing reliance on a single revenue stream.
Deployment pressure is also playing a role here. Where new platform opportunities are limited, funds are increasingly investing behind existing assets, accelerating consolidation strategies within their portfolios.
“We’re seeing more funds adopt buy-and-build, even those that haven’t historically focused on it. It’s become a core part of how they think about growth.”
Marcus Archer, Managing Partner
Conviction-led investing and earlier engagement
Another clear shift is how private equity firms are identifying and pursuing opportunities.
Rather than casting a wide net, funds are becoming more focused. Most are narrowing in on a small number of sectors where they have strong conviction and a clear value creation strategy.
This is being supported by more proactive, “outside-in” work. Funds are building relationships with target businesses and advisers well before a formal process begins, and in many cases are forming views on assets months or even years in advance.
The impact is significant. By the time a process launches, the most prepared buyers are already well positioned to act decisively.
“Continuation vehicles have moved from being a niche solution to a core part of how funds manage exits and extend value creation.”
Marcus Archer, Managing Partner
The growing influence of PE-backed buyers
The role of private equity-backed portfolio companies in M&A continues to expand.
These businesses are increasingly competing head-to-head with both traditional trade buyers and private equity funds for new acquisitions. With the backing of institutional capital and the agility of a corporate acquirer, they are often able to move quickly and present compelling strategic cases.
In many processes, they are now among the most credible bidders.
At the same time, there is growing interest from US-backed portfolio companies looking to expand into Europe. While this hasn’t yet fully translated into completed deal volumes, the level of activity and intent is increasing, suggesting a more competitive and internationally driven market ahead.
Continuation vehicles gain momentum
Continuation vehicles have also become a more prominent feature of the private equity landscape.
Once viewed as a niche solution, they are now a mainstream route for managing portfolio dynamics. For funds holding strong-performing assets that require more time or capital, continuation vehicles offer a way to deliver liquidity to existing investors while retaining exposure to future upside.
This trend has accelerated quickly, with continuation-led exits now accounting for a significantly larger share of overall activity.
For the mid-market in particular, this presents a growing opportunity, both in terms of deal flow and the need for tailored financing and advisory support.
A market defined by discipline and opportunity
Taken together, these dynamics point to a private equity market that is more disciplined, more focused, and increasingly strategic in how it operates.
Funds are still active. Capital is still available. But success is now defined by preparation, conviction, and the ability to navigate complexity, rather than simply participating in a rising market.
For high-quality businesses, the opportunity remains significant. But as with the broader M&A landscape, outcomes are becoming more selective, and execution is relying more heavily on getting the fundamentals right from the outset.
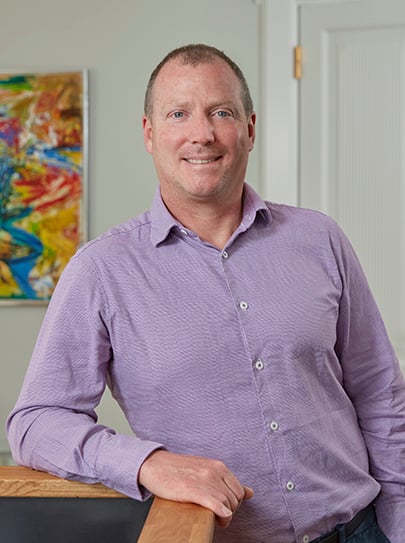
Author
Marcus Archer
Managing Director
I have been a part of Clearwater since 2008, and during that time have built a business services sector team, developed our sponsor coverage programme, substantially grown our London team and sat on the UK Board (as well as advising many clients on successful fundraises, exits or acquisitions!). I am still a keen tennis player, rapidly learning how to play padel, an average golfer and love any time I can spend scuba diving or on the ski slopes.
Transactions
Not just numbers on a balance sheet, our transactions represent over 20 years’ commitment to our clients’ future. Helping them change the game. Even before it was ready to be changed.
Major new investment into one of the fastest-growing technology providers in the UK
Adviser to LDC on its new round of investment in Aspire Technology Solutions
Financing to support the expansion strategy of an Italian insurance brokerage company
Adviser to Wide Group, a portfolio company of Pollen Street Capital, in raising a loan from funds managed by BlackRock

Leading frozen food services provider secures new ownership
Adviser to NPM on its envisaged acquisition of Elbfrost and related acquisition financing

Supporting a landmark aerospace deal in defence-grade visualisation
Adviser to Tikehau Capital on its acquisition of Scioteq
Our annual report
Explore our other insights and dive into the full report for a detailed look at our latest findings and forecasts.