The consumer sector has remained one of the most complex and closely watched areas of the market over the past 12 months. While headlines continue to point to pressure on spending, the underlying picture is more nuanced.
At a structural level, the consumer is in relatively strong financial health across the UK and Europe. Household balance sheets are robust, savings rates remain elevated, and wage growth has, in many cases, outpaced inflation. The challenge isn’t the capability to spend, but consumer confidence.
As a result, behaviour has become more selective and more polarised. Higher income cohorts are doing fine, lower income groups are finding life much tougher.
Premium and value segments are both performing well, while mid-market propositions are under increasing pressure. This shift is shaping both strategic decision-making and investor appetite across the sector.
“We’re seeing a clear bifurcation. Consumers are either trading up or trading down, and the middle ground is losing share.”
MARTIN AGERUP, PARTNER AND HEAD OF CONSUMER
At the same time, investor demand is concentrating around a number of more resilient categories. Travel, health and wellness, food and drink, and pet-related sectors continue to attract robust levels consumer spend, while leisure and hospitality have faced weaker demand following the post-COVID rebound, combined with a “perfect storm” of operating cost headwinds.
Alongside macroeconomic pressures, structural shifts in consumer behaviour are continuing to reshape the sector in unexpected ways.
One of the most talked-about developments has been the rapid rise of GLP-1 weight loss drugs and their broader impact on consumption patterns. What began as a healthcare trend is now influencing multiple areas of consumer spend, from food consumption and dining habits through to travel, fitness, and apparel.
“The impact goes far beyond food. It’s starting to influence how people think about spending across a whole range of categories.”
Martin Agerup, Partner and Head of Consumer
While the full implications are still emerging, it’s clear that these types of behavioural shifts are creating both risks and opportunities across the market.
At the same time, recommerce and circular models are gaining traction, particularly among younger consumers. Platforms focused on second-hand and resale are seeing increased adoption, reflecting both value-conscious purchasing and changing attitudes towards ownership.
Digital transformation and the changing path to purchase
Digital transformation continues to play a central role in the sector, although the narrative has evolved. The shift towards online-only models has stabilised, and in some areas has begun to reverse slightly. Consumers are increasingly engaging with brands across both physical and digital channels, with omni-channel now firmly established as the dominant model.
At the same time, the way consumers discover products is changing rapidly. AI-driven search, shifts in digital marketing effectiveness, and the rise of new platforms such as TikTok Shop are all reshaping customer acquisition strategies.
Traditional performance marketing channels are becoming more expensive and less predictable, while organic visibility is increasingly shaped by AI-led search tools. As a result, brands are having to adapt quickly, experimenting with new routes to market and new ways of engaging with customers.
We completed 27 consumer transactions with a total value of €2bn in FY25/26
Clearwater’s approach: Focus, relationships, and sector depth
In a market that hasn’t been easy for several years, our consumer team has maintained strong momentum by focusing on the areas that matter most.
“We’ve stayed focused on the bright spots in the consumer economy which is where most of the M&A is being seen. That’s allowed us to stay active and deliver great outcomes, even in a tough market.”
MARTIN AGERUP, Partner and Head of Consumer
The team has completed 27 deals across Europe in FY 25/26, and has consistently outperformed expectations, supported by deep sector expertise and long-standing relationships across both private equity and strategic buyer communities.
This relationship-led approach is central to the team’s success. By maintaining an active dialogue with both buyers and business owners, the team is able to stay close to evolving demand and identify opportunities early.
“We don’t give easy advice. We give good advice. That’s what builds long-term relationships and gets deals done.”
MARTIN AGERUP, PARTNER AND HEAD OF CONSUMER
The team’s long-term commitment to the sector has also been a differentiator. While some competitors have scaled back their consumer coverage, we’ve continued to invest, strengthening our position and benefiting from increased market share as a result.
Cost pressures and an uncertain outlook
Inflationary pressures, wage increases, and higher energy and distribution costs have all impacted margins, particularly in more labour-intensive areas such as retail, leisure and hospitality.
Geopolitical developments are also adding another layer of uncertainty. The conflict in the Middle East is already impacting energy prices and supply chains, which could feed through into further cost pressures across the sector.
While the extent of this impact remains unclear, it highlights how external shocks continue to influence both consumer confidence and business performance.
Investment dynamics: selective but active
Against this backdrop, investment activity remains selective but active.
Large consumer groups are continuing to streamline portfolios, driving carve-out activity and creating opportunities for investors to acquire focused, high-quality assets. At the same time, private equity appetite remains strongest in areas with clear structural growth drivers, particularly health, wellness, and premium consumer segments.
Sustainability remains part of the investment conversation, particularly through themes such as circular economy and responsible sourcing. However, it’s no longer the primary driver of decision-making. Instead, it tends to act as an additional layer of attractiveness rather than a standalone investment thesis.
Clearwater’s approach: Focus, relationships, and sector depth
In a market that hasn’t been easy for several years, our consumer team has maintained strong momentum by focusing on the areas that matter most.
“We’ve stayed focused on the bright spots in the consumer economy which is where most of the M&A is being seen. That’s allowed us to stay active and deliver great outcomes, even in a tough market.”
MARTIN AGERUP, Partner and Head of Consumer
The team has completed 27 deals across Europe in FY 25/26, and has consistently outperformed expectations, supported by deep sector expertise and long-standing relationships across both private equity and strategic buyer communities.
This relationship-led approach is central to the team’s success. By maintaining an active dialogue with both buyers and business owners, the team is able to stay close to evolving demand and identify opportunities early.
“We don’t give easy advice. We give good advice. That’s what builds long-term relationships and gets deals done.”
MARTIN AGERUP, PARTNER AND HEAD OF CONSUMER
The team’s long-term commitment to the sector has also been a differentiator. While some competitors have scaled back their consumer coverage, we’ve continued to invest, strengthening our position and benefiting from increased market share as a result.
Outlook: cautious confidence
Looking ahead, the consumer sector is expected to remain dynamic and, at times, unpredictable. Confidence may take time to recover, and external factors will continue to influence sentiment. However, the fundamentals remain in place for future growth.
“There’s still plenty of opportunity. It’s about being in the right places and understanding where growth is really coming from.”
MARTIN AGERUP, PARTNER AND HEAD OF CONSUMER
For well-positioned businesses, and for investors with conviction, the sector continues to offer attractive opportunities. Success will depend on understanding shifting consumer behaviours, adapting to new routes to market, and focusing on the areas where demand is most resilient.
And as the past year has shown, those who stay close to the detail and remain confident in their approach will continue to find ways to succeed.
Head of Consumer
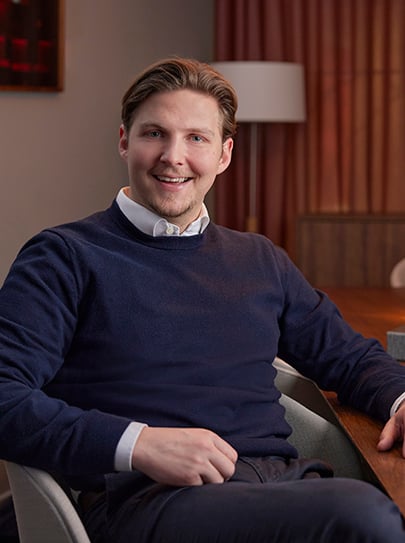
Martin Agerup
Partner
As a partner at our Stockholm office, I lead Clearwater's international Consumer team. I have spent most of my career in M&A and joined Clearwater in 2015. It's been an incredible time, having been part of building both our team and track record.
Find your local consumer sector team
Get to know the experienced professionals driving results for our clients.
Transactions
Not just numbers on a balance sheet, our transactions represent over 20 years’ commitment to our clients’ future. Helping them change the game. Even before it was ready to be changed.
Building Europe's leading educational travel group
Adviser to KKR-backed Travelopia on its sale of Experience Education to Rockaway Capital
Creating the leading Arctic hospitality and destination group across Finland and Norway
Adviser to Katja Ikäheimo-Länkinen and Ilkka Länkinen on SantaPark Arctic World’s strategic partnership with Arctic Resort Company
Swedish car care leader partners for international growth
Adviser to tershine on its partnership with Relais Group
Leading manufacturer of wild bird feed under new, strong ownership
Adviser to Nordic Pet Care Group on its sale of VPG Wild Bird
Our annual report
Explore our other insights and dive into the full report for a detailed look at our latest findings and forecasts.