Overview of M&A activity
In Q4 2024, the automotive industry continued to face major challenges, exacerbated by heightened global uncertainty, stemming from the unknown impact of the US elections and a slower-than-expected EV transition. Despite lower interest rates and stagnating inflation figures, suppliers remain risk-averse to investments. Overall, the production forecast for the short term has been revised, slightly down compared to the previous year, although moderate growth is still expected in the long term.
The automotive M&A deal count decreased from Q3 2024 to Q4 2024 with 88 and 74 transactions, respectively. In Q4 2024, M&A activity was driven by transactions in the areas of interior and aftermarket suppliers, new mobility solutions providers such as autonomous driving and charging solutions, as well as financial sponsor-backed deals, including the acquisition of DVS Production GmbH and DVS Production South GmbH by Accursia Capital GmbH, and KI USA Corporation acquired by American Industrial Acquisition Corporation.
In Q4 2024, M&A activity was driven by transactions in the areas of interior and aftermarket suppliers, new mobility solutions providers such as autonomous driving and charging solutions, as well as financial sponsor-backed deals
Top M&A deals Q4 2024
- Embotech AG, a Swiss-based provider of cutting-edge autonomous driving solutions for logistics, with a focus on Automated Vehicle Marshalling (AVM) in passenger car factories and Autonomous Terminal Tractors (ATT) at port terminals and logistic centres, secured a €25.3m (CHF 23.5m) in Series B funding to support the company’s scale of its AVM and ATT solutions in Europe, and ultimately in the US, Middle East, and Asia. The funding round was led by Emerald Technology Ventures and Yttrium, with additional funds from BMW i Ventures, Nabtesco Technology Ventures, and others
- Cerma Srl, a developer and manufacturer of high-precision components for the off-highway and industrial markets including hydraulic valves and manifolds, acquired by DexKo Global Inc. (DexKo), a leading manufacturer of engineered components for trailers, recreational vehicles, and towable equipment. The acquisition enhances DexKo’s hydraulics value chain, expanding its product portfolio, and is expected to leverage synergies in manufacturing capabilities and expertise, particularly in turning, milling, and grinding applications
- Arnott LLC, a global leader in the design and manufacturing of air suspension products and accessories for the automotive aftermarket, acquired by US-based private equity firm, MidOcean Partners LLP (MidOcean). This acquisition marks MidOcean’s fourth investment in the automotive aftermarket sector over the past five years and positions Arnott LLC for its next phase of growth. With MidOcean’s extensive experience and network in the industry, Arnott LLC aims to further innovate its suspension technologies and strengthen its leadership in the global aftermarket space
Across Europe, a mixed performance in valuation multiples was observed from Q3 2024 compared to Q4 2024, with EV/Sales and EV/EBITDA multiples increasing by 6.3% and 9.6%, respectively, while EV/EBIT decreased by 1.0%. The North American market demonstrated a strong negative performance, with EV/Sales, EV/EBITDA, and EV/EBIT multiples decreasing by 7.3%, 6.3%, and 11.7% in Q4 2024, respectively. In Asia, an overall increase was observed, with EV/Sales, EV/EBITDA, and EV/EBIT multiples increasing by 7.9%, 10.4%, and 14.9%, respectively, compared to Q3 2024.
The pace of the powertrain transformation is expected to be largely impacted by regulatory and geopolitical developments in the future. Suppliers continue to face challenges, like lower volumes, and transformation demand, to adapt product portfolios to industry trends. Lower interest rates remain a catalyst for investments in research and development, and a key driver for strategic alliances and M&A activity.
Top M&A deals Q4 2024
- Embotech AG, a Swiss-based provider of cutting-edge autonomous driving solutions for logistics, with a focus on Automated Vehicle Marshalling (AVM) in passenger car factories and Autonomous Terminal Tractors (ATT) at port terminals and logistic centres, secured a €25.3m (CHF 23.5m) in Series B funding to support the company’s scale of its AVM and ATT solutions in Europe, and ultimately in the US, Middle East, and Asia. The funding round was led by Emerald Technology Ventures and Yttrium, with additional funds from BMW i Ventures, Nabtesco Technology Ventures, and others
- Cerma Srl, a developer and manufacturer of high-precision components for the off-highway and industrial markets including hydraulic valves and manifolds, acquired by DexKo Global Inc. (DexKo), a leading manufacturer of engineered components for trailers, recreational vehicles, and towable equipment. The acquisition enhances DexKo’s hydraulics value chain, expanding its product portfolio, and is expected to leverage synergies in manufacturing capabilities and expertise, particularly in turning, milling, and grinding applications
- Arnott LLC, a global leader in the design and manufacturing of air suspension products and accessories for the automotive aftermarket, acquired by US-based private equity firm, MidOcean Partners LLP (MidOcean). This acquisition marks MidOcean’s fourth investment in the automotive aftermarket sector over the past five years and positions Arnott LLC for its next phase of growth. With MidOcean’s extensive experience and network in the industry, Arnott LLC aims to further innovate its suspension technologies and strengthen its leadership in the global aftermarket space
Transactions
Not just numbers on a balance sheet, our transactions represent over 20 years’ commitment to our clients’ future. Helping them change the game. Even before it was ready to be changed.
Innovator in autonomous driving solutions secures funding to support the growth of logistics automation solutions
Adviser to Embotech on its new funding
Leading machinery specialist strengthens position with strategic sale
Adviser to DVS TECHNOLOGY GROUP on the sale of DVS Production and DVS Production South to Accursia Capital
Palatine exits Direct Tyre Management with secondary buy-out by Caledonia
Adviser to Palatine-backed Direct Tyre Management on its sale to Caledonia Private Capital
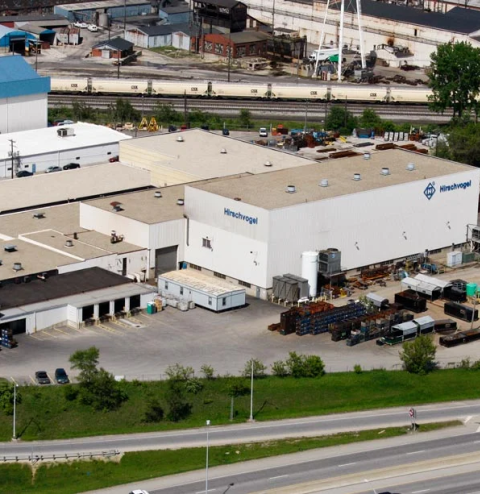
Sale of a specialist in the forging and machining of steel parts for OEMs, Tier-1, and industrial clients
Adviser to Hirschvogel on the sale of its US production facility to Mutares
Our international automotive team




Tobias Schätzmüller
Managing Partner +49 172 670 45 43 tobias.schaetzmueller@clearwatercf.com Connect